- contact@divsystems.in
- Mon - Fri: 10.30 am - 7.30 pm
We are creative, ambitious and ready for challenges! Hire Us
Overview
Div Systems built the operating system for a textile warehousing business that stores fabric for merchant clients and charges for the space, covering receipt, roll-level location, partial release, and billing by package type and period.
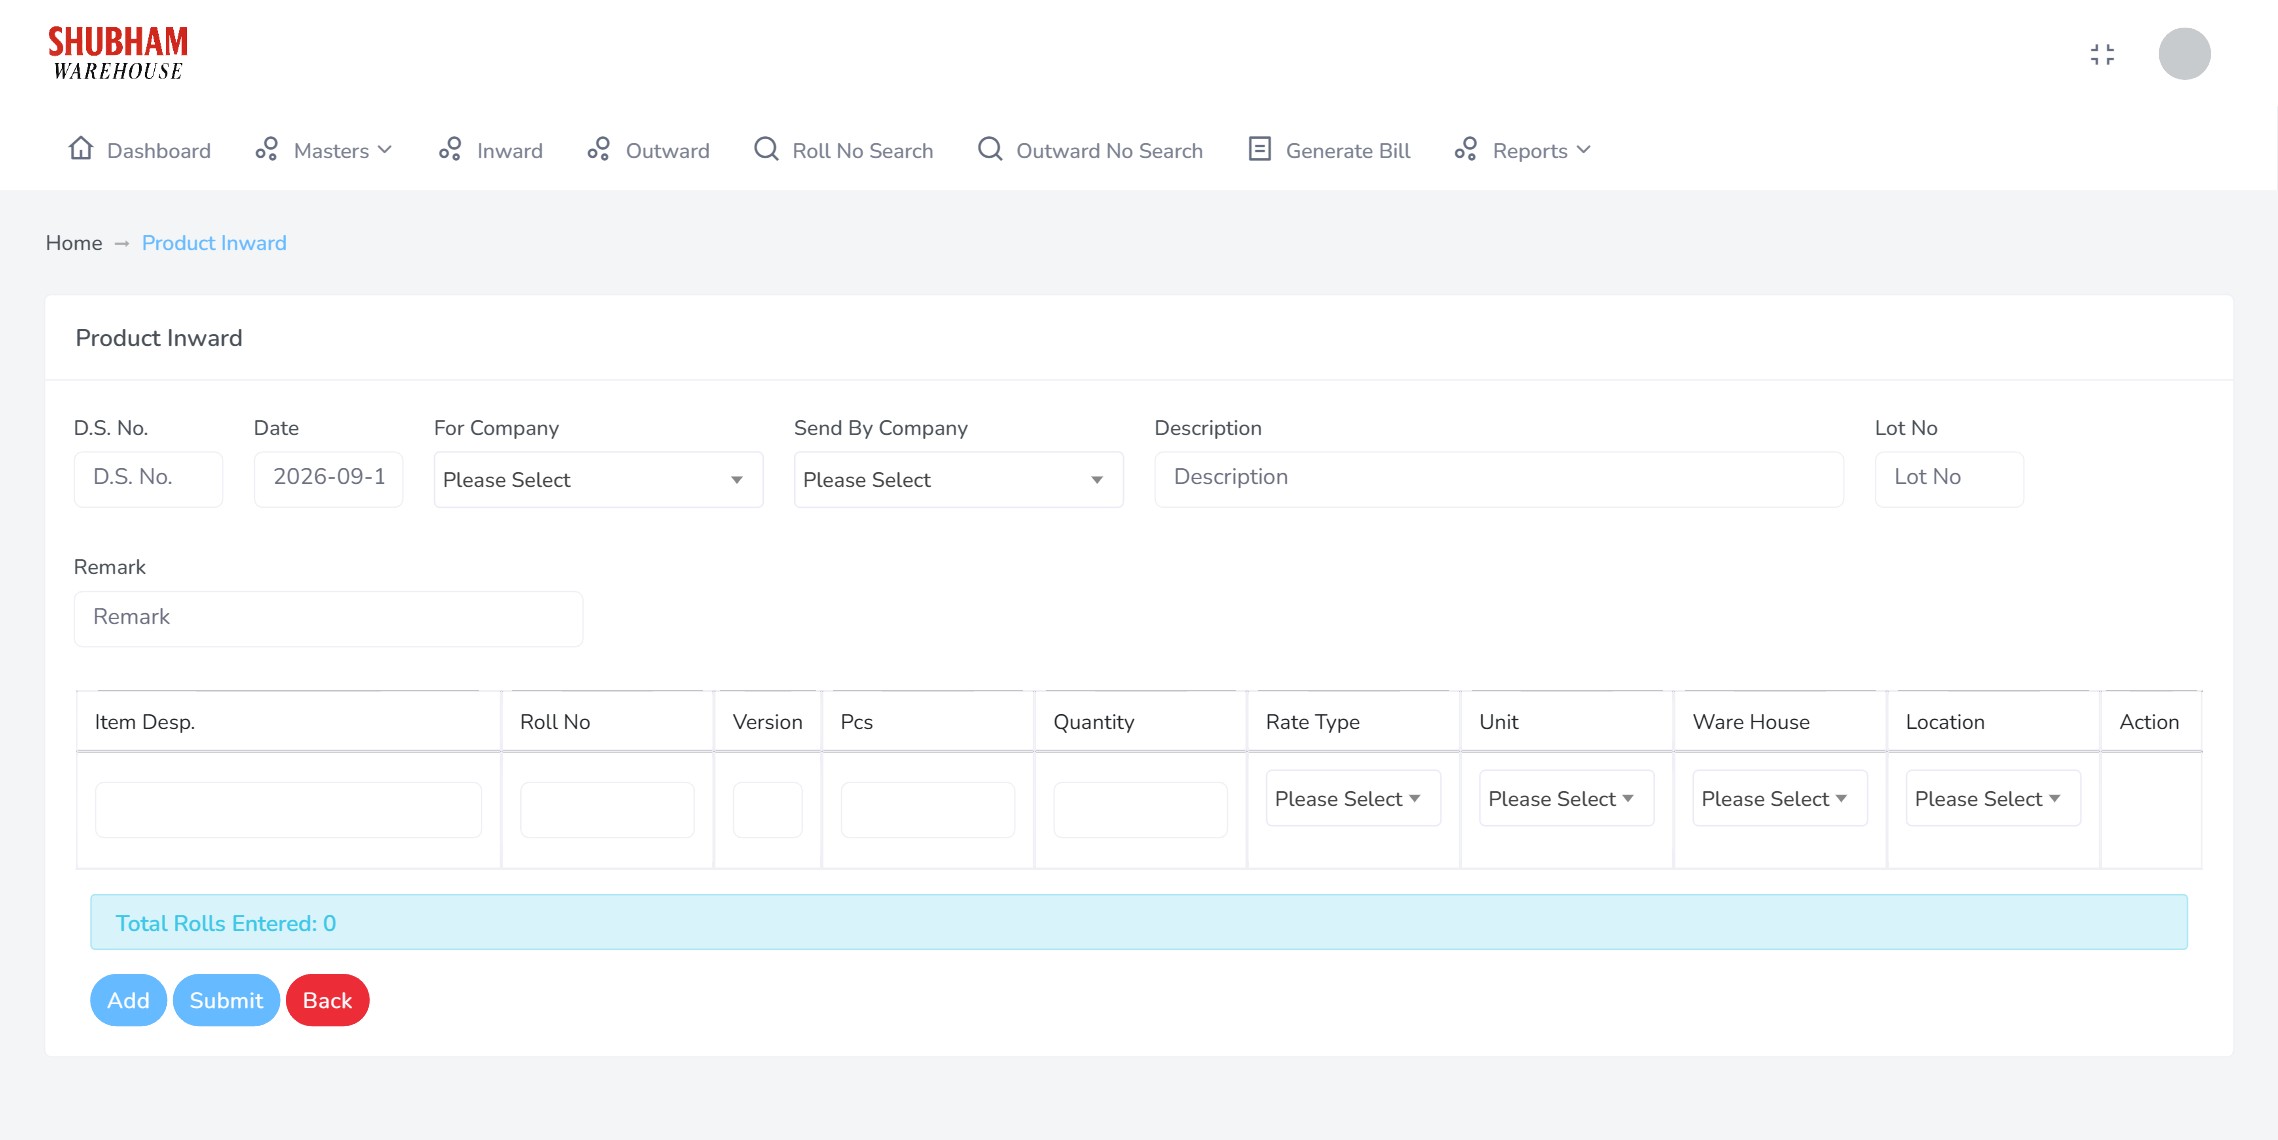
Goods arrive against a despatch slip for a named client and are recorded roll by roll with lot number, pieces, quantity, package type, warehouse and location. Release happens against a delivery challan to a named party, in whole or in part. Rates are held per client, per warehouse, per package type, and bills are generated monthly, weekly or daily from what was actually held and handled.
Business need
A storage business does not own what it holds. In Indian law the arrangement is a bailment: the merchant is the bailor, the warehouse is the bailee, and under section 151 of the Contract Act the warehouse must take as much care of the goods as a person of ordinary prudence would take of their own. Ownership never moves. What the warehouse actually sells is space, time and custody.
That makes the record the product. Section 35(2) of the CGST Act binds every owner or operator of a warehouse or godown to maintain records of consignor, consignee and other details, and it applies whether or not the operator is registered. The manner is prescribed by Rule 58, and Rule 58(4)(b) is unusually specific: the operator must keep books of accounts covering the period for which particular goods remain in the warehouse, including particulars of despatch, movement, receipt and disposal.
Read that again against a storage business. The statutory record and the billing basis are the same data. A system that keeps one properly produces the other.
The stakes for getting custody wrong are documented. At a state warehousing corporation godown in Karnataka, twelve of fourteen pledged lots were found entirely missing, with misappropriation at that single godown put at over twenty-five crore rupees. At a warehouse in Madhya Pradesh, roughly 95,000 bags of pledged stock had gone; the operator alleged the depositors had removed them on forged documents, the depositors alleged the operator's own staff were responsible, and both accounts were internally coherent. That is what a custody dispute looks like when release authority is not tied to an auditable trail.
So the business needed a system that could:
Our solution
Every inward line creates an identified roll with its own number, version, piece count, quantity, package type and physical location. A consignment is a collection of those, not a single quantity that can only be counted in aggregate.
Modelling it that way is what makes the rest possible. Partial release becomes arithmetic on a specific roll rather than a note in a register. A query about one roll returns its client, its lot, its remaining pieces and its shelf. And because package type sits on the line, the same record that proves custody also carries the basis on which the storage is charged.
The receipt also separates the client from the sender, because in this trade the party who owns the fabric and the party whose vehicle delivers it are routinely different, and conflating them is how consignments end up attributed to the wrong account.
Key features
Each roll carries its own number and version alongside pieces and quantity, so stock is a set of identified items rather than a running total.
Receipts record both the client whose goods these are and the company that delivered them, which are frequently not the same party.
The merchant's own lot reference is carried through, so the warehouse and the client can talk about the same goods in the same terms.
Every line is placed in a specific warehouse and location, which is what turns a stock figure into something a person can walk to.
Roll, bale, parcel, box and their trade variants are recorded per item, because that is the unit the storage is charged on.
Outward entry shows current pieces against pieces being released, so part of a lot can leave while the balance stays under custody.
Releases record the party, the delivery destination, the transporter, the challan number and the delivery address.
Any roll can be looked up directly to return its client, description, remaining pieces, package type, warehouse and location.
Releases are searchable by their own reference, so a past despatch can be produced when a client queries it.
Rates are held by client, warehouse and package type, which is how a storage business actually prices rather than by a single tariff.
Bills are generated per client for the chosen period, including a six or seven day week option, with loaded and unloaded quantities.
Inward, outward, combined movement and stock reports run per client and date range, with export to CSV, Excel and PDF.
The current position prints as a summary, which is what gets handed over during a physical verification.
Every inward and outward record prints as a PDF document for the client and the driver.
Users, warehouses, locations, clients and transporters are all maintained as masters with permissions applied per user.
Inside the platform
Screens from the live system. Client names, transporters, despatch references and rates are masked; structure and workflow are unchanged.
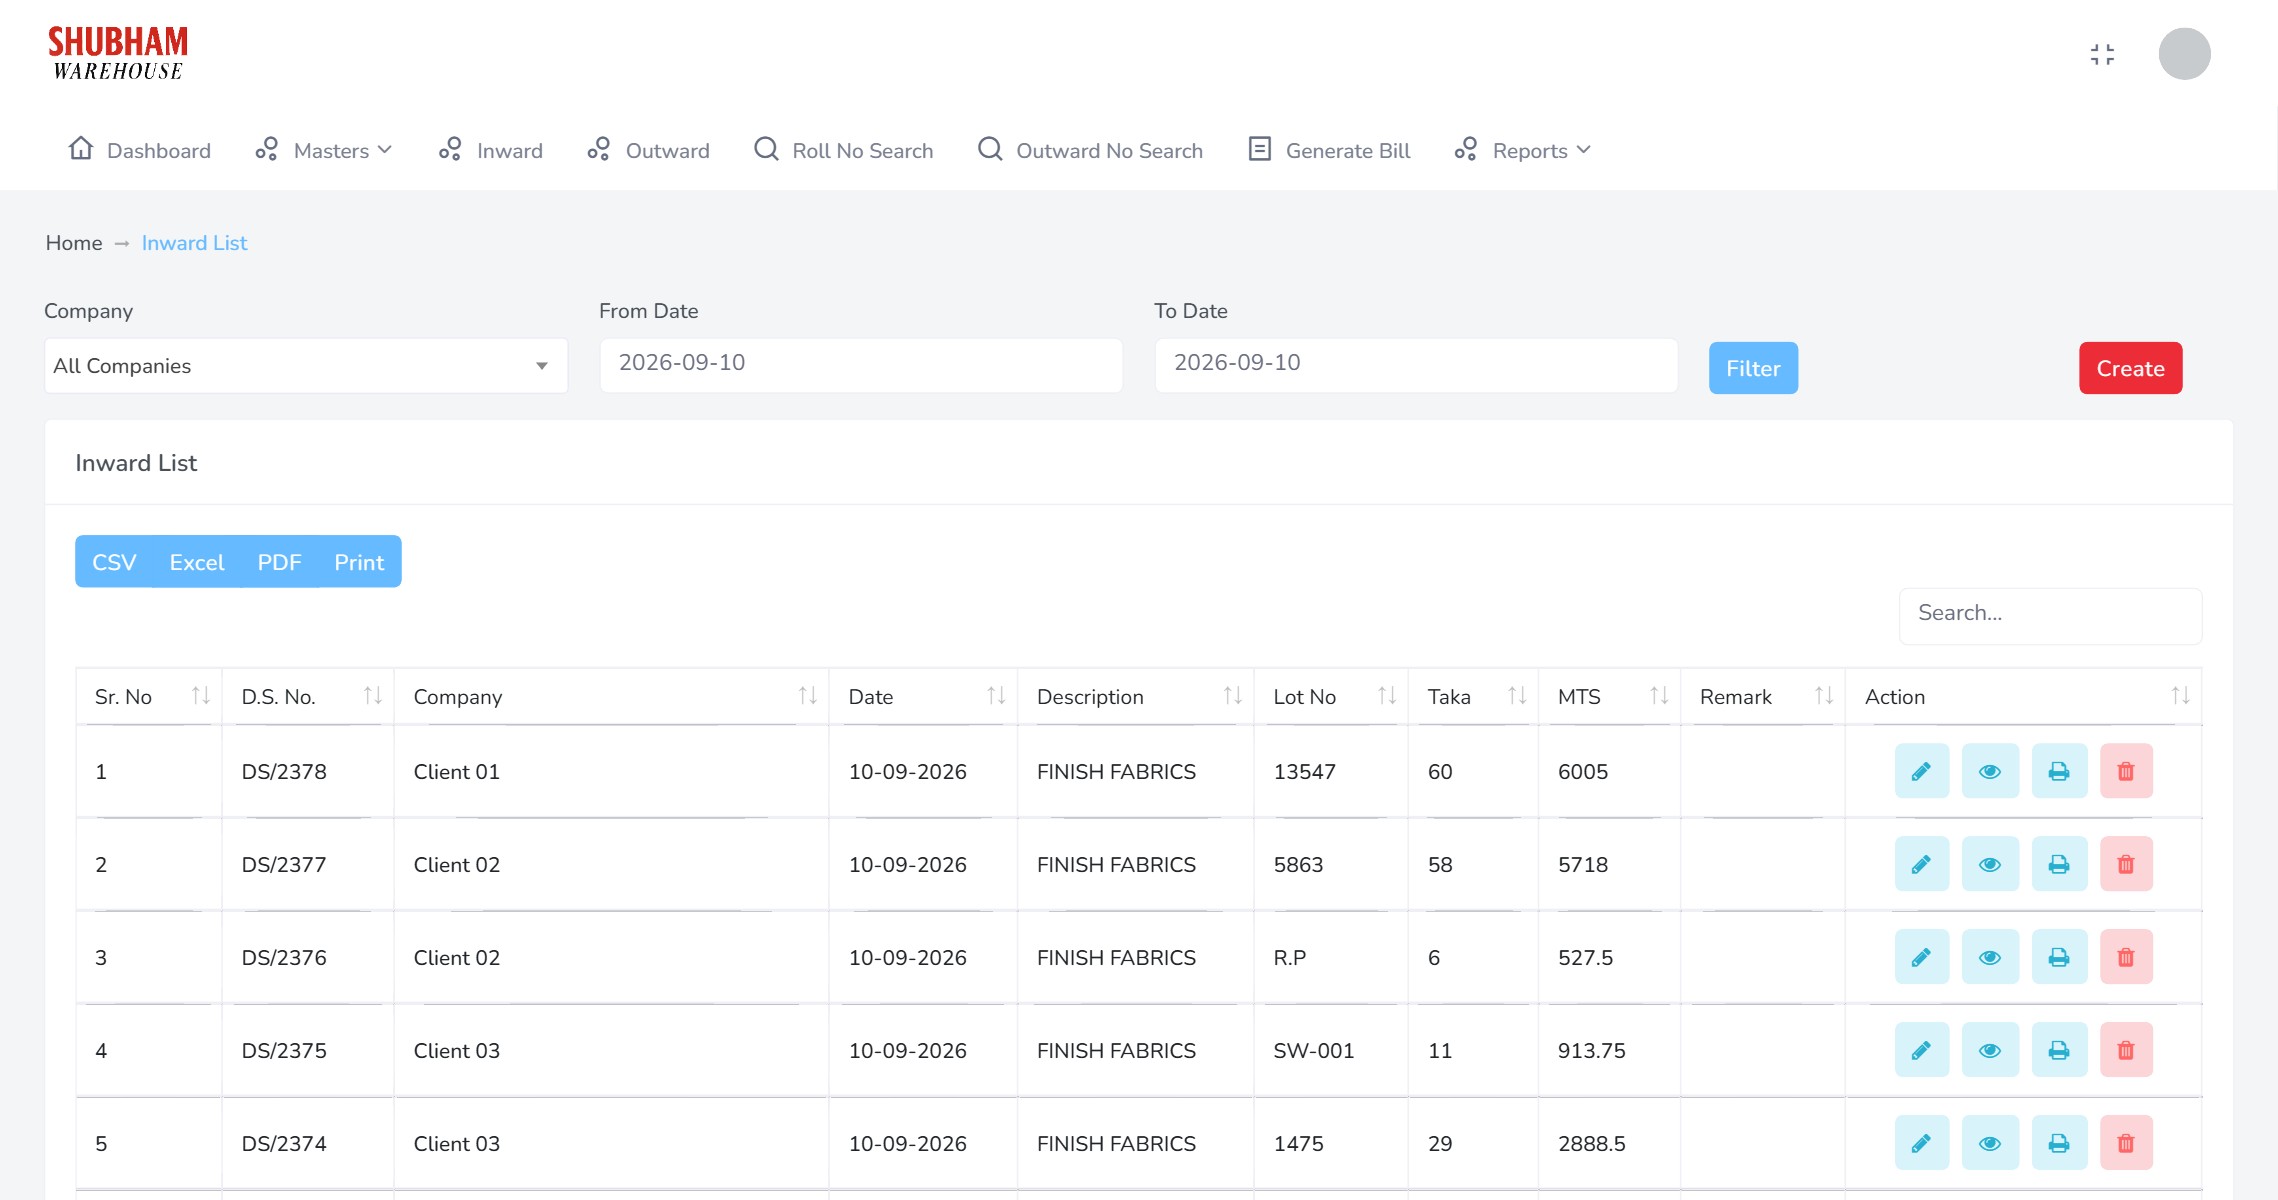
The inward register lists every receipt with its despatch slip number, client, date, description, lot number, piece count and metres. Filtered by client and date range, exportable, and printable per entry.
This is not administrative housekeeping. Rule 58 requires a warehouse operator to keep books covering the period for which particular goods remain in the warehouse, with the particulars of receipt, movement, despatch and disposal, and it binds the operator whether or not they are registered for tax. A system that records arrivals and releases against identified goods produces that record as a by-product of trading.
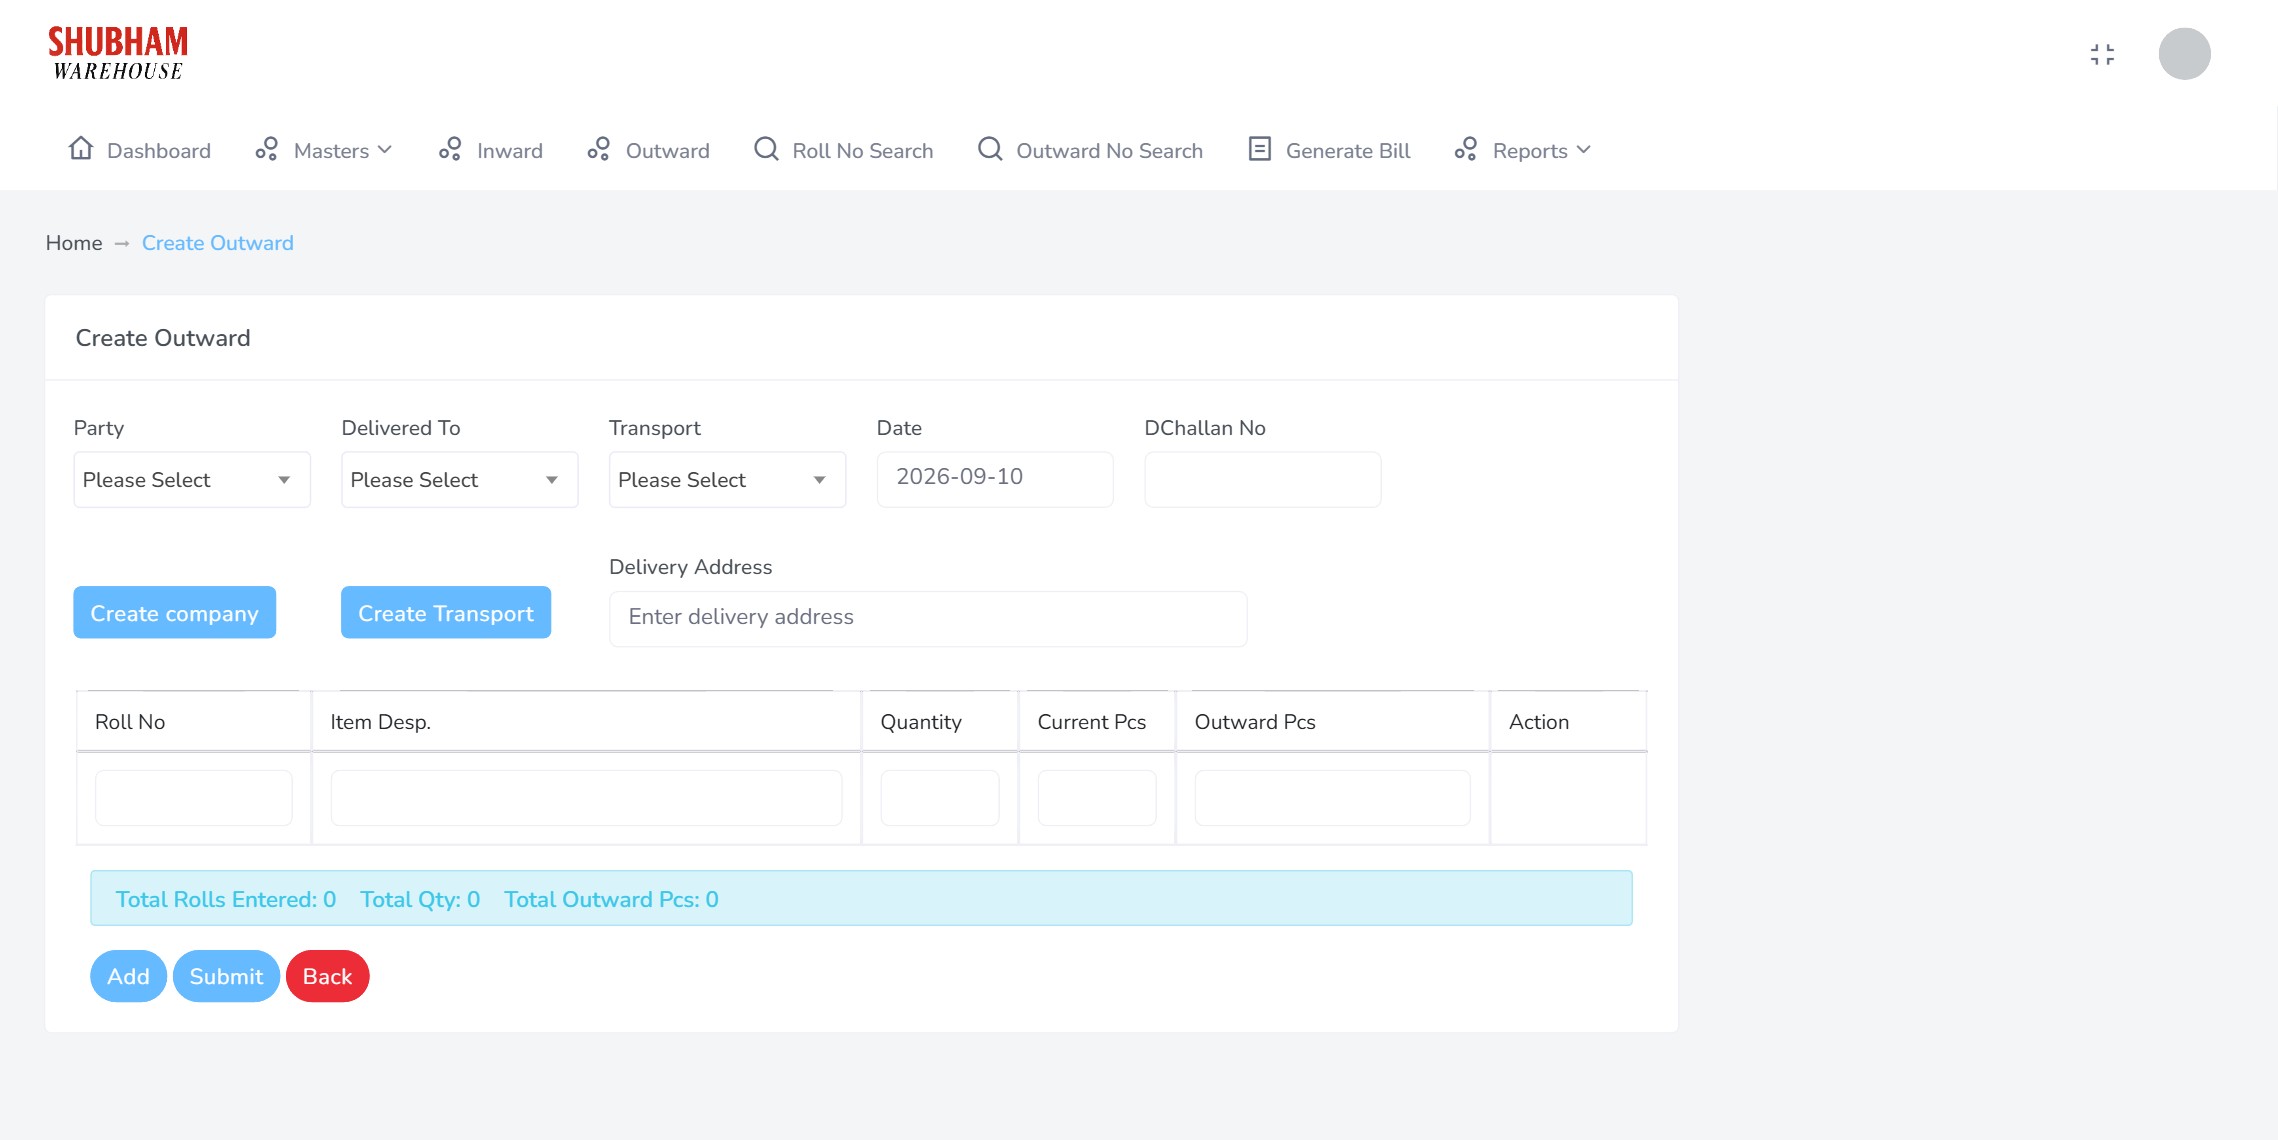
Release records the party instructing it, where the goods are going, the transporter, the challan number and the address, then decrements specific rolls by specific piece counts.
Under the Contract Act a bailee must deliver according to the bailor's directions, and good faith protects the warehouse only where delivery followed those directions. The documented disputes in Indian warehousing are almost always about exactly this: stock is gone, the operator says the depositor took it on forged papers, the depositor says the operator's staff removed it, and there is no record capable of settling it. The control is not a better lock. It is a timestamped release trail tied to a named instructing party.
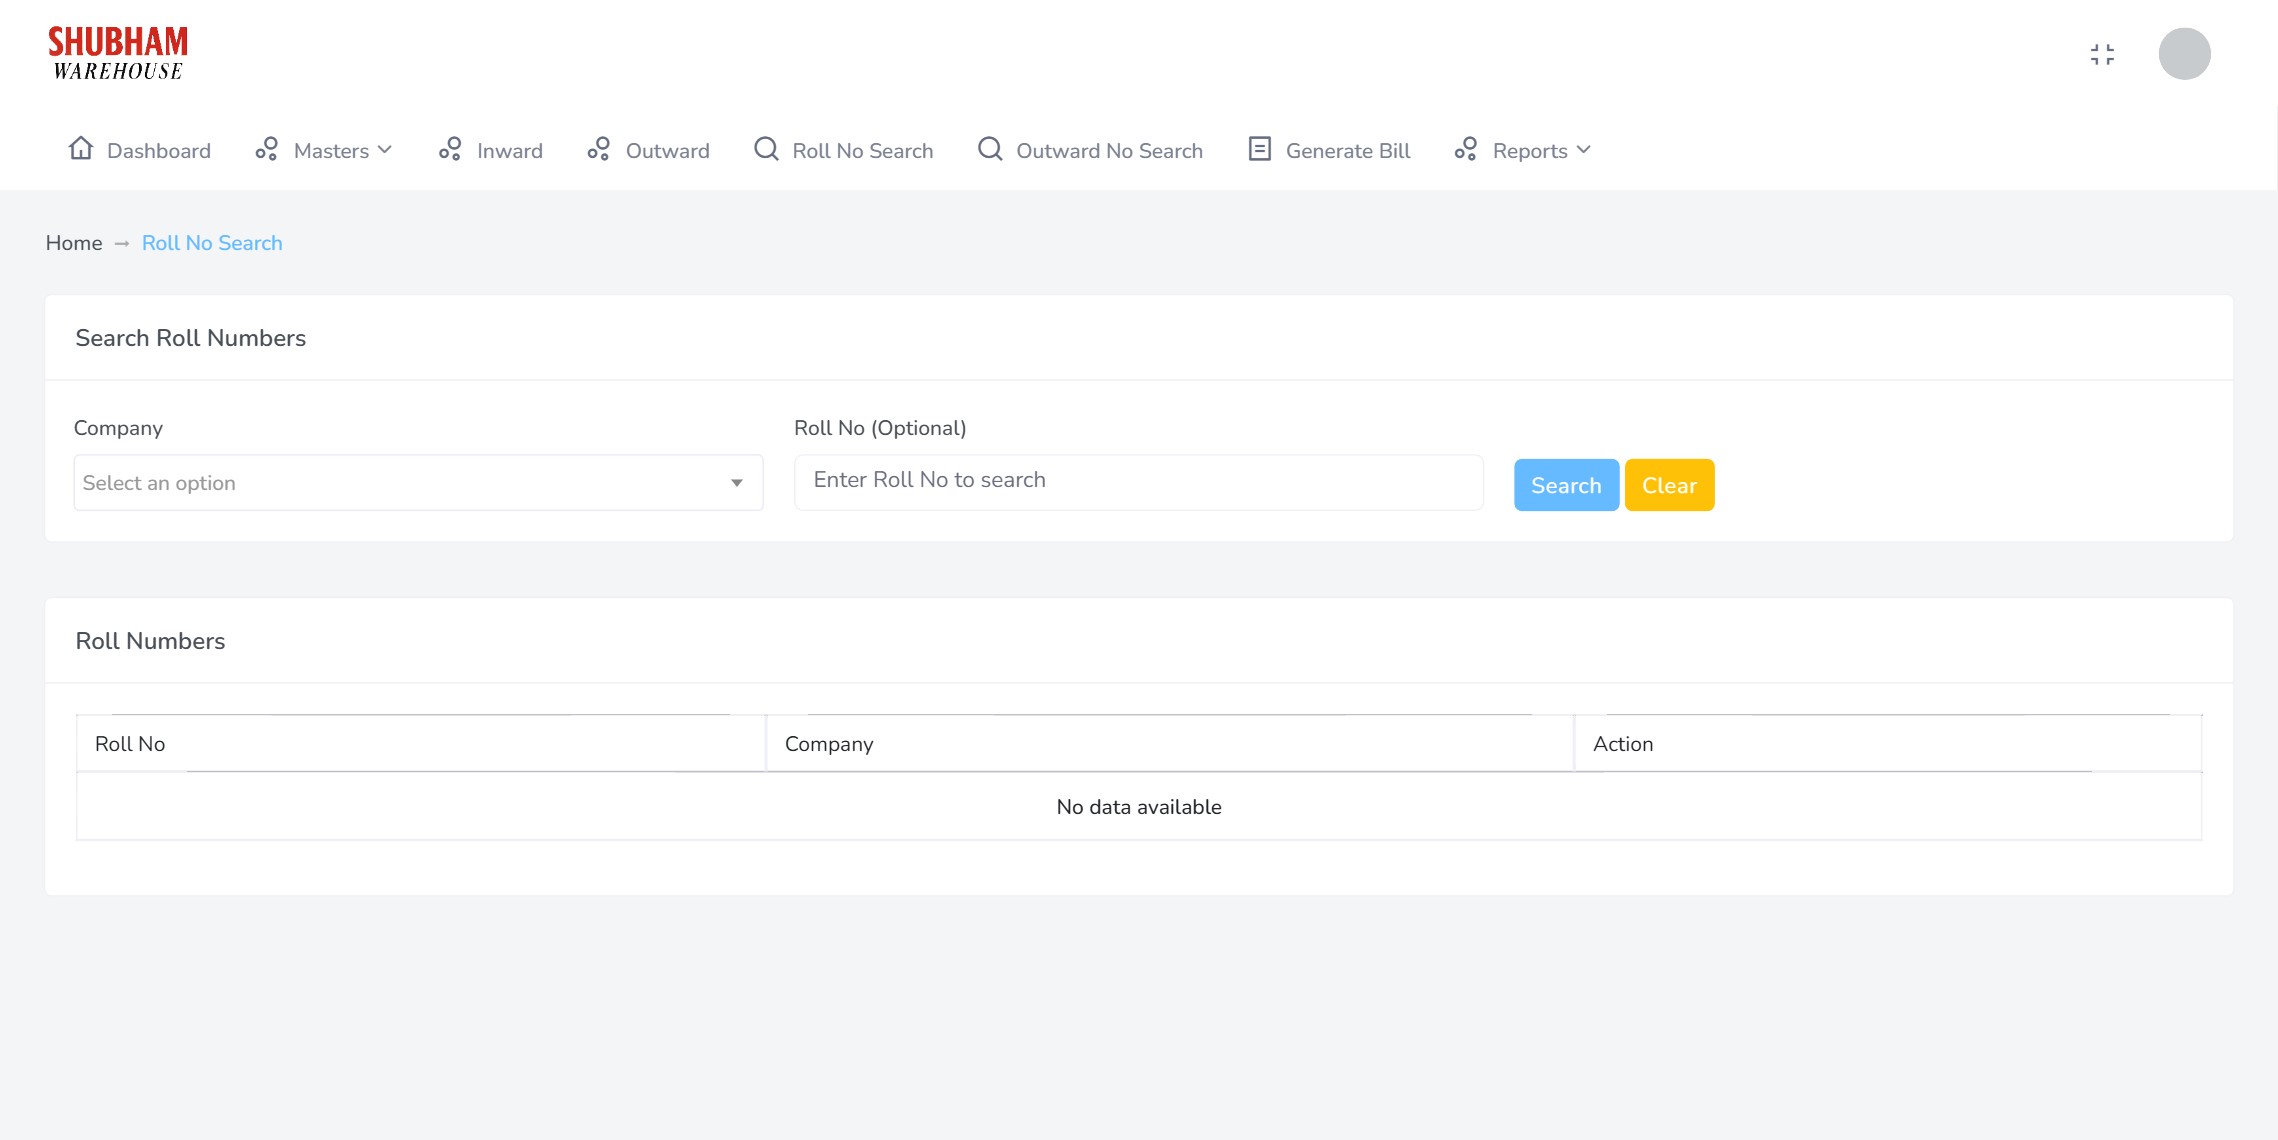
Roll number search returns the client, item description, roll number, version, original and current pieces, quantity, package type, warehouse and location. Outward numbers are searchable on the same principle.
In day-to-day trading this is the screen that gets used most, because the questions a storage business receives are nearly always specific. A client asks whether a particular lot is still with you, how much of it remains, and where it is. A total held figure cannot answer any of those.
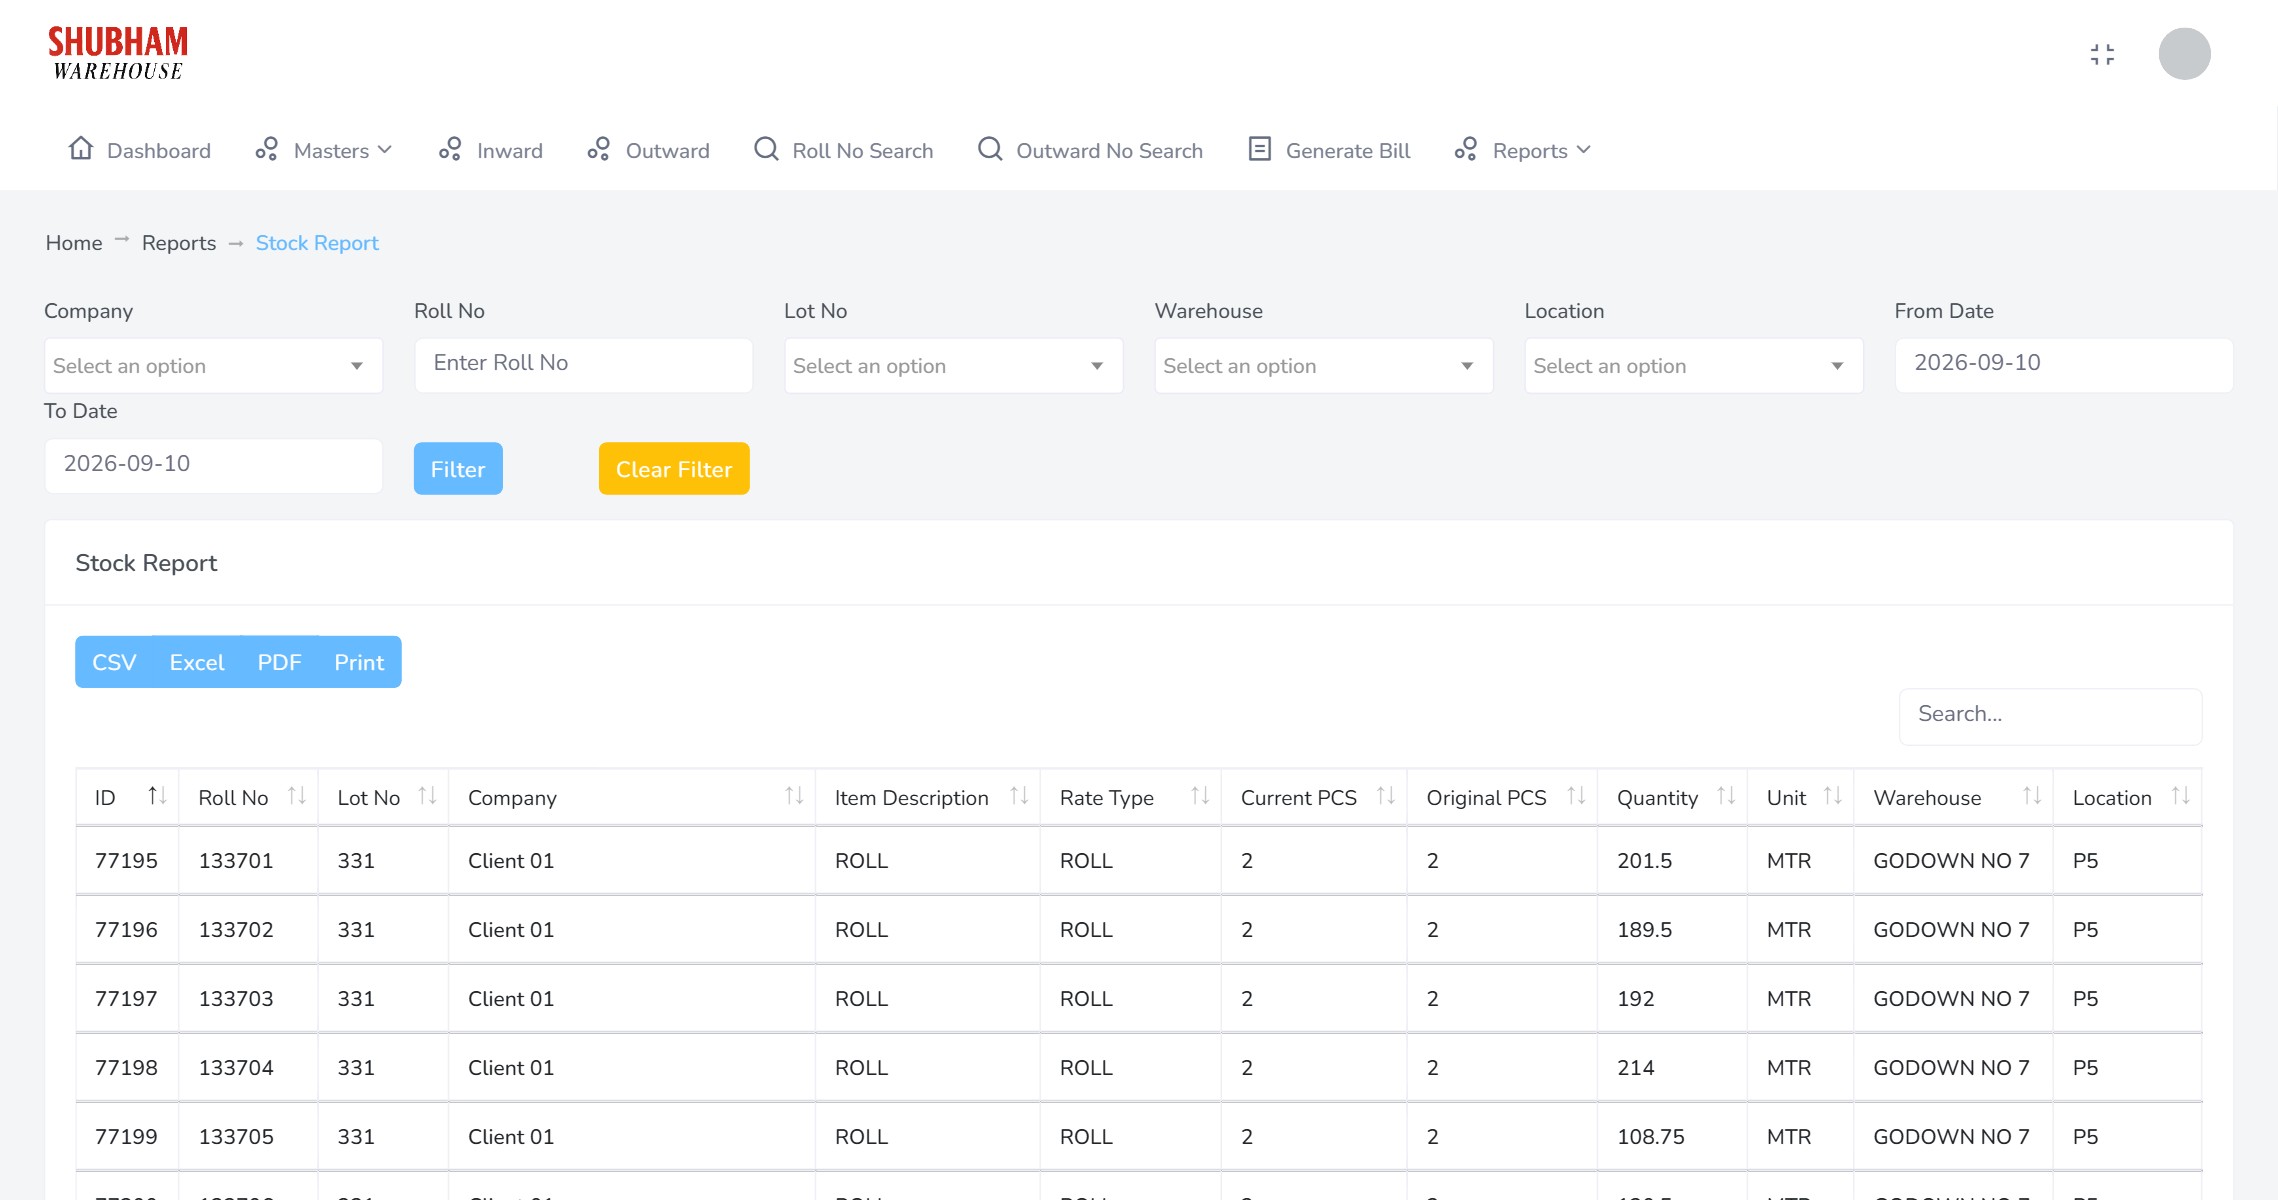
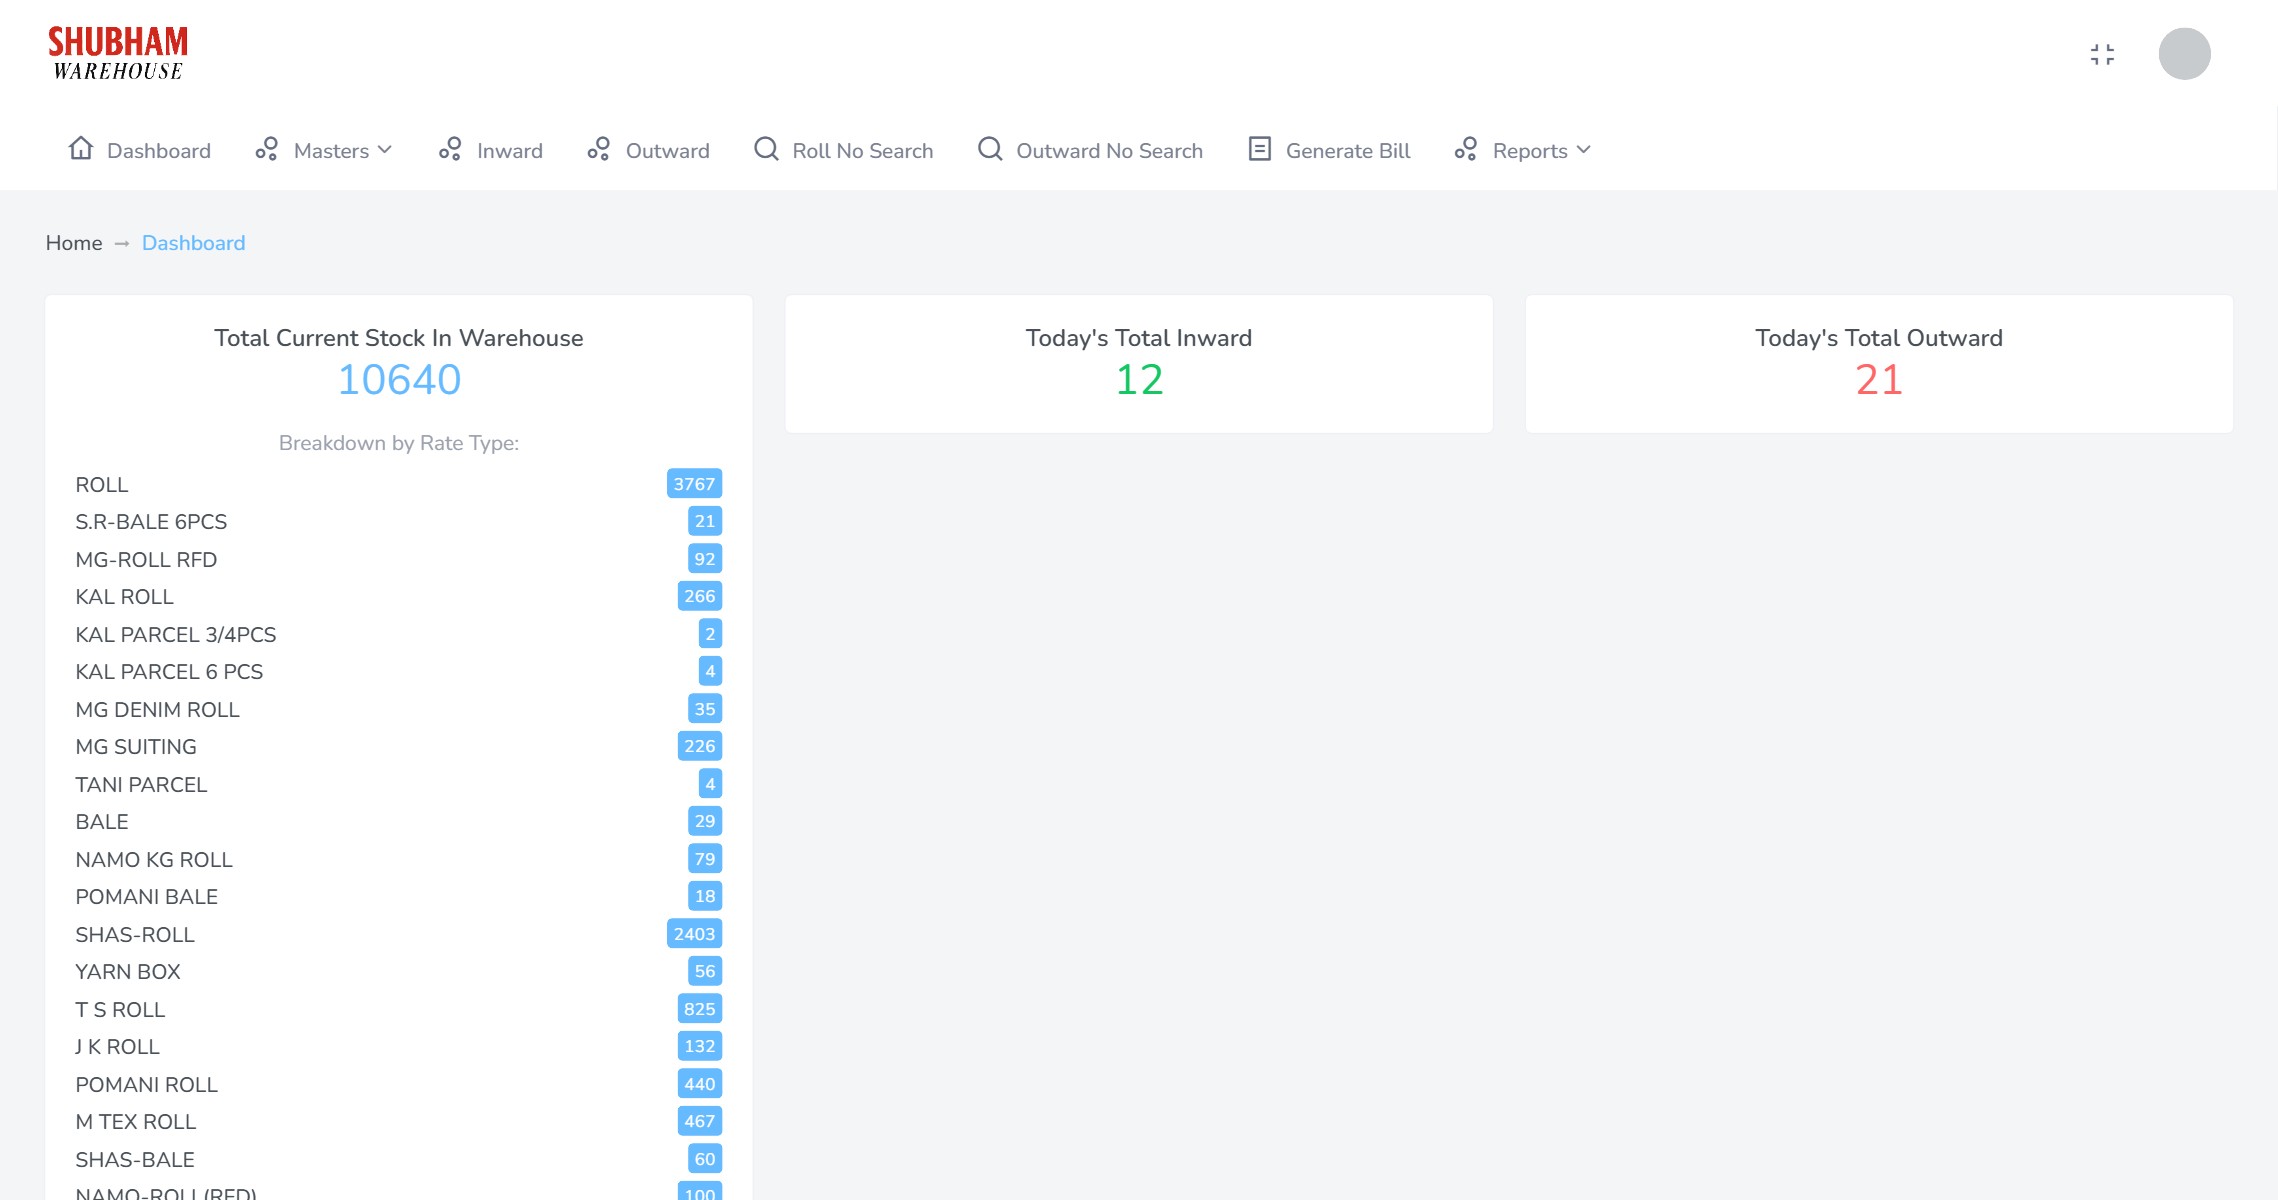
Stock reports run per client and date range, and the current position prints as a summary. The dashboard carries the same total broken down by package type.
The Karnataka case is instructive here. The failure was not an absent ledger. It was the absence of independent physical verification against the ledger, in a system where a godown manager's assertion of quantity was simply accepted. A printable position by client and location is what makes an independent count possible, and the rules contemplate exactly that by requiring the operator to facilitate physical verification on demand.
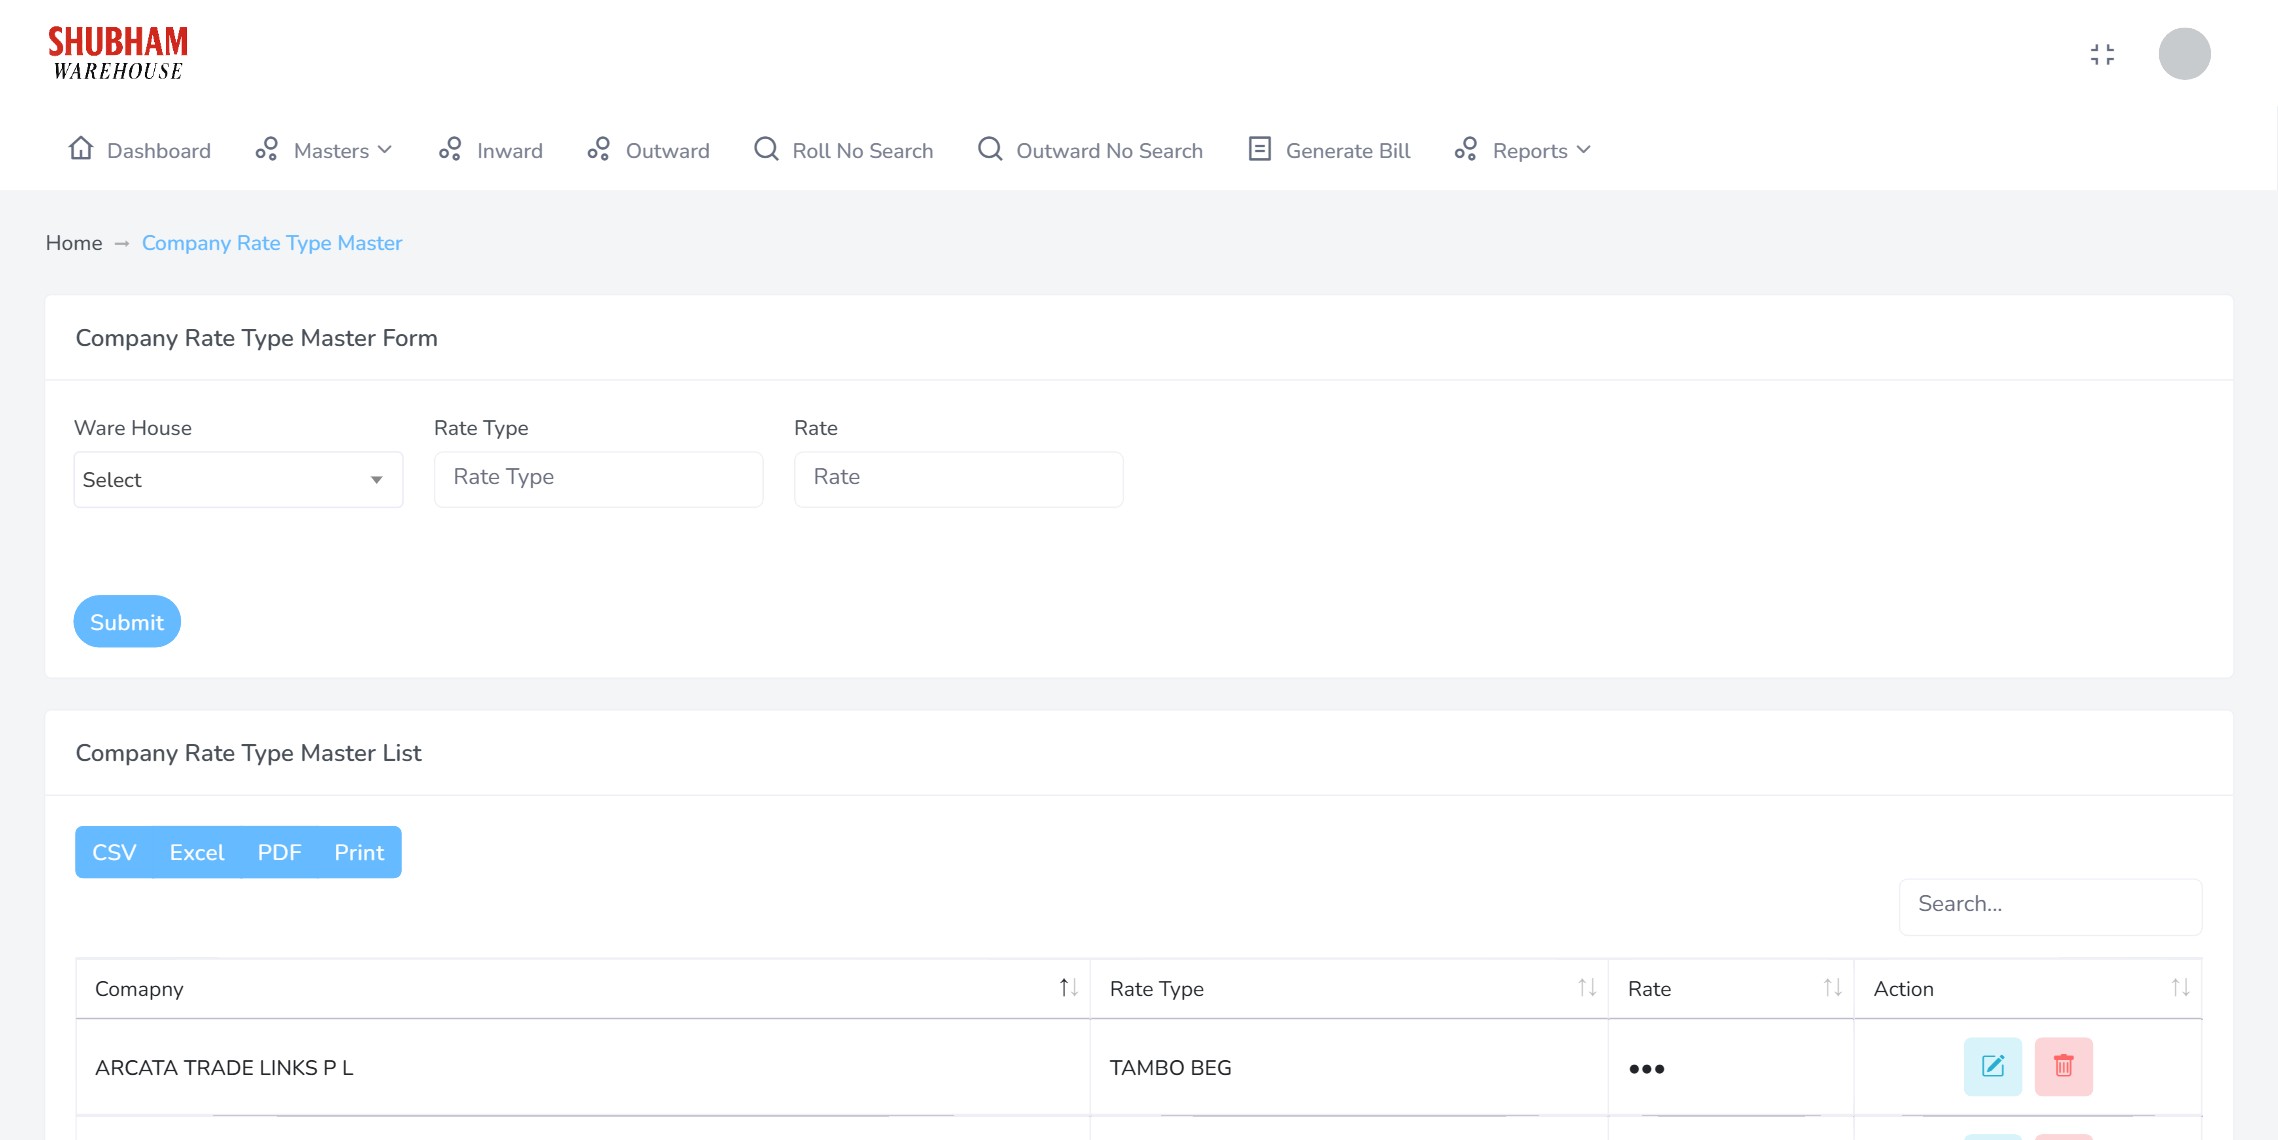
The rate card holds a rate for each combination of client, warehouse and package type. That granularity reflects how the trade prices: a bale and a roll occupy different space, a long-standing client is on different terms from a new one, and a covered godown is not a shed.
Keeping rates as data rather than in a negotiator's memory is also what makes a bill defensible when a client queries it, since the rate applied can be shown alongside the quantity it was applied to.
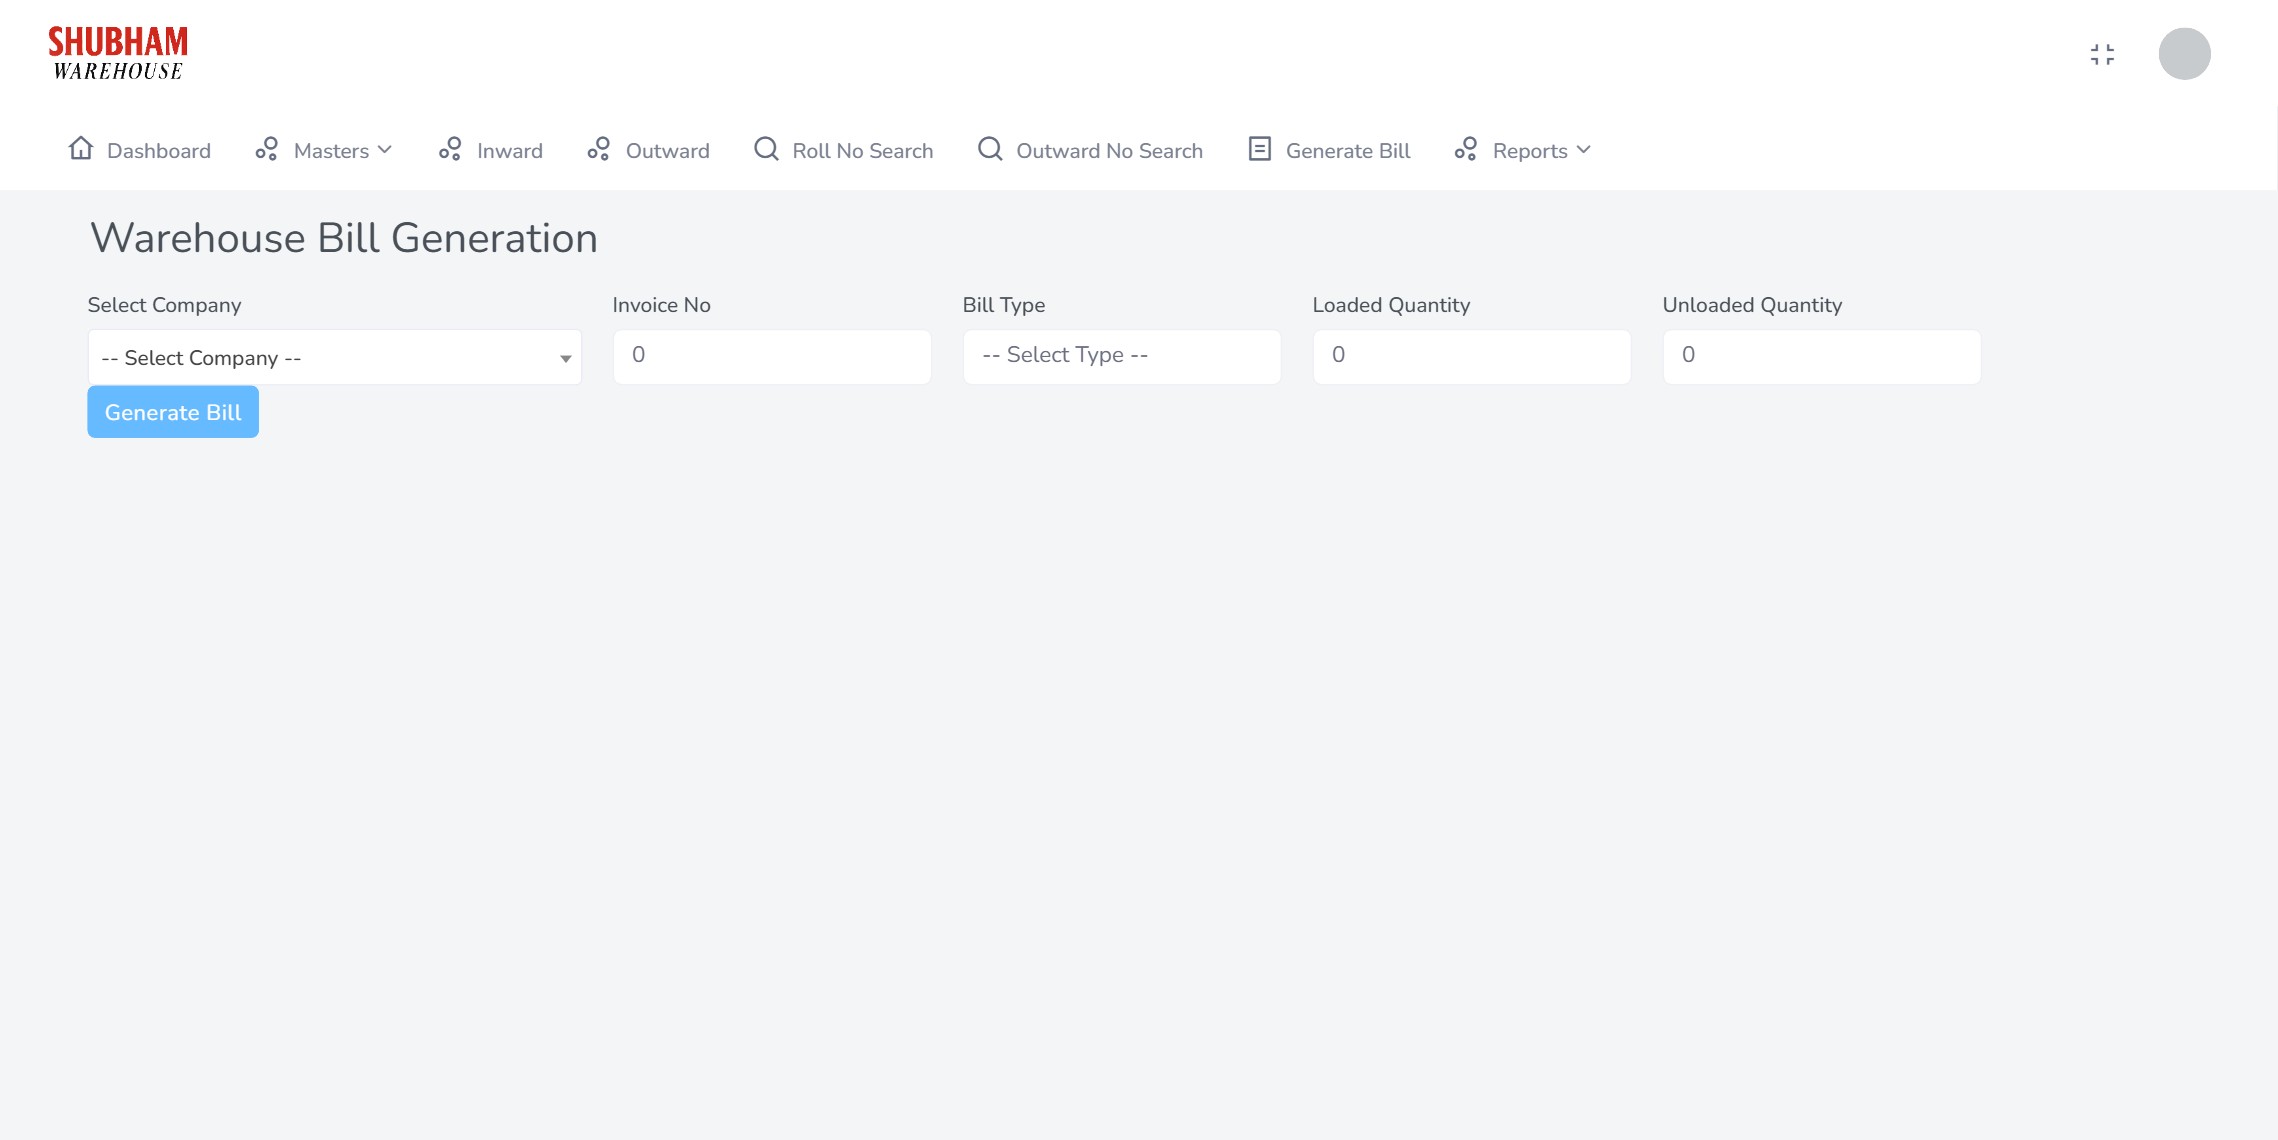
A bill is raised per client for a selected period, with the loaded and unloaded quantities alongside the holding. Because the underlying records carry package type and dates, the charge follows what was actually held and handled rather than an estimate.
Two things are worth stating plainly for anyone in this business. Storage of textiles is a taxable service at eighteen per cent under the storage and warehousing classification; the exemption for agricultural produce does not reach fabric or yarn, and even raw cotton lost that exemption in July 2022. And where handling is supplied with storage to the same client in the ordinary course, it is generally a composite supply taxed at the rate of the storage.
End to end
Custody begins at the first line and does not end until the last piece has left.
Impact
Custody is evidenced. Receipt and release both name a party and carry a document reference, which is what settles a dispute rather than starting one.
Partial release is safe. Taking half a lot out leaves an accurate balance rather than an approximate one.
Enquiries are answered in seconds. A roll number returns owner, remaining pieces and shelf without walking the floor.
Billing follows the record. The same data that proves custody produces the invoice, so the two cannot drift apart.
Counts can be verified. A printed position by client and location makes an independent check possible.
The statutory record exists already. Period of storage with receipt and disposal particulars falls out of normal trading.
Engineering approach
Modelling the roll rather than the consignment is what makes partial release, location and enquiry work. Everything else follows from that decision.
In this trade the party who owns the fabric and the party who delivers it routinely differ, and merging them misattributes stock.
Keeping original and remaining counts as distinct fields preserves history while giving an accurate present balance.
Recording it on the line rather than the client means the billing basis is captured at the moment of custody, not reconstructed later.
Client, warehouse and package type together, because a single tariff cannot express how storage is actually negotiated.
The custody record and the billing basis are the same rows, which removes the reconciliation step that usually sits between them.
Common questions
Section 35(2) of the CGST Act requires every owner or operator of a warehouse or godown to maintain records of consignor, consignee and other relevant details, and it applies whether or not the operator is registered. Rule 58 prescribes the manner, and Rule 58(4)(b) requires books of accounts covering the period for which particular goods remain in the warehouse, including particulars of despatch, movement, receipt and disposal. An operator not otherwise registered enrols electronically to obtain an enrolment number.
Not automatically, and this is widely misunderstood. Section 170 of the Contract Act gives a particular lien only where the bailee has exercised labour or skill that improves the goods, and the Allahabad High Court has held that merely storing goods in a godown for payment does not qualify. Section 171 lists who has a general lien, bankers, factors, wharfingers, attorneys and policy-brokers, and states that no other person does. A warehouse is not on that list. Retention therefore depends on an express contractual lien in the storage agreement, and even then a lien is possessory and carries no power of sale.
No. Storage and warehousing falls under the supporting services in transport heading and attracts eighteen per cent. The exemption for loading, unloading, packing, storage or warehousing applies to agricultural produce as defined, which fabric and yarn are not, since spinning and weaving are not processing usually done by a cultivator. Even raw cotton lost its exemption with effect from 18 July 2022.
A delivery challan under Rule 55 of the CGST Rules, not a tax invoice, because moving goods to a warehouse for storage is not a supply. The rule expressly covers transportation for reasons other than by way of supply, and the challan is issued in triplicate. An e-way bill is separately required where consignment value crosses the threshold, including for movements that are not supplies.
Because the questions a storage business is asked are specific. Whether a particular lot is still held, how much of it remains after a partial delivery, and where it physically sits. It also matters in a dispute: an aggregate figure cannot show which goods were released, to whom and when, whereas a roll-level trail can.
The structure suits any third-party storage business that holds identifiable units for multiple owners and charges by unit and period. What changes is the package types, the rate structure and the identity scheme for the stored item. Those are master data, so adaptation is configuration rather than redevelopment.
Why Div Systems
We build operational systems for businesses whose records have to stand up later, to a client, an auditor or a court. The work starts by walking the floor and reading the obligations behind the process, and ends with something the people doing the work will keep current.
Start your project